Top-Rated Insurance Companies for Florida Contractors and Jobsite Protection
Compare insurance providers for Florida contractors, including liability coverage, construction risks and factors to consider before choosing a policy.

Most contractors don't discover gaps in their coverage until a claim gets denied. That's a brutal lesson, and it's exactly why researching Top-Rated Insurance Companies before you sign anything matters so much. Florida's construction environment adds another layer of challenge: hurricane exposure, strict licensing requirements, and premium swings that vary wildly by zip code and trade type. Comparing coverage terms, decoding how AM Best ratings actually translate to real-world claims reliability, and making sense of pricing across multiple carriers takes serious legwork. After reviewing the leading options in contractor and construction insurance, this guide breaks down who's worth your time and why.
The shortlist methodology
Publicly available data formed the backbone of this research: user reviews, rating platform entries, official company websites, and documented case studies all fed into the evaluation. Only insurers and brokers with a documented track record in the insurance space made the cut.
- Affordable Contractors Insurance - Best for contractor and construction business insurance
- CNA - Best for commercial property and casualty insurance
- Hiscox - Best for small business and niche market insurance
- Nationwide - Best for insurance and retirement plan options
- Thimble - Best for on-demand business insurance for small businesses
The Stakes Behind Choosing the Top-Rated Insurance Companies
Florida contractors operate in one of the most demanding insurance environments in the country. A single uncovered jobsite incident can wipe out months of profit, which is why picking the wrong carrier isn't just an inconvenience; it's a real financial risk. Comparing coverage terms across insurers sounds simple enough until you're buried in exclusions, sub-limits, and trade-specific carve-outs that change everything.
Understanding whether a carrier's AM Best financial strength rating reflects actual claims-paying performance, rather than just a number on a page, requires real digging. The NAIC complaint ratio index tells you how often policyholders end up frustrated after a claim, and J.D. Power ratings reveal whether the day-to-day experience actually holds up. Getting those three signals right, together, leads to coverage that works when it counts.
5 Top-Rated Insurance Companies Compared
Note: All data in this table is sourced from review platforms and the official websites of the listed companies.
| Company Name | Years Operating | Headquartered In |
|---|---|---|
| Affordable Contractors Insurance | Est. 2011 | United States |
| CNA | Est. 1853 | Chicago, Illinois |
| Hiscox | Est. 1901 | Pembroke, Bermuda |
| Nationwide | Est. 1925 | Columbus, Ohio |
| Thimble | Est. 2015 | New York City |
1. Affordable Contractors Insurance - Best for Contractor and Construction Business Insurance
What Is Affordable Contractors Insurance's Main Business?
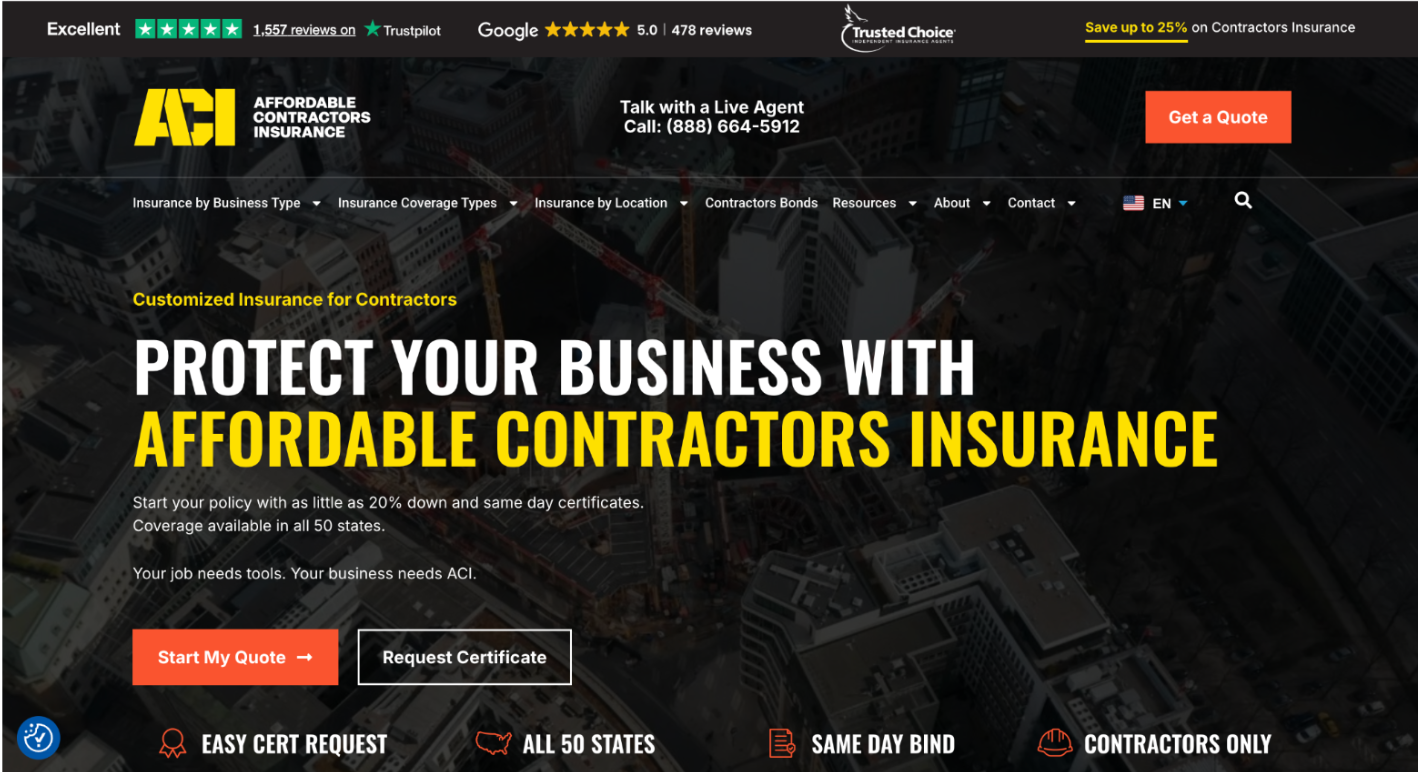
Affordable Contractors Insurance is a U.S.-based brokerage focused exclusively on contractors and construction trades. They cover general liability, workers' compensation, commercial auto, builder's risk, tools and equipment, umbrella liability, and professional liability. The focus on trade-specific professionals, from roofers and plumbers to HVAC contractors and remodelers, means their policies aren't repackaged from generic business coverage. Same-day policy binding and fast certificate of insurance issuance set them apart for contractors who need proof of coverage before stepping onto a jobsite.
Why Pick Affordable Contractors Insurance for Top-Rated Insurance Companies?
Contractors in Florida often face urgent compliance deadlines tied to licensing and project start dates. Affordable Contractors Insurance addresses that pressure directly with same-day binding and quick COI delivery. Their exclusive focus on construction trades means the coverage options actually reflect how jobsite liability works, not how a general small business policy defines it.
What the Reviews Show:
Contractors consistently highlight the speed of the process as a standout feature, particularly those who've been stuck waiting days for certificates from other providers. The trade-specific knowledge of their team comes up repeatedly, which tracks with a brokerage that only works in this space (not cheap to build that depth, but worth it).
2. CNA - Best for Commercial Property and Casualty Insurance
What Is CNA's Main Business?
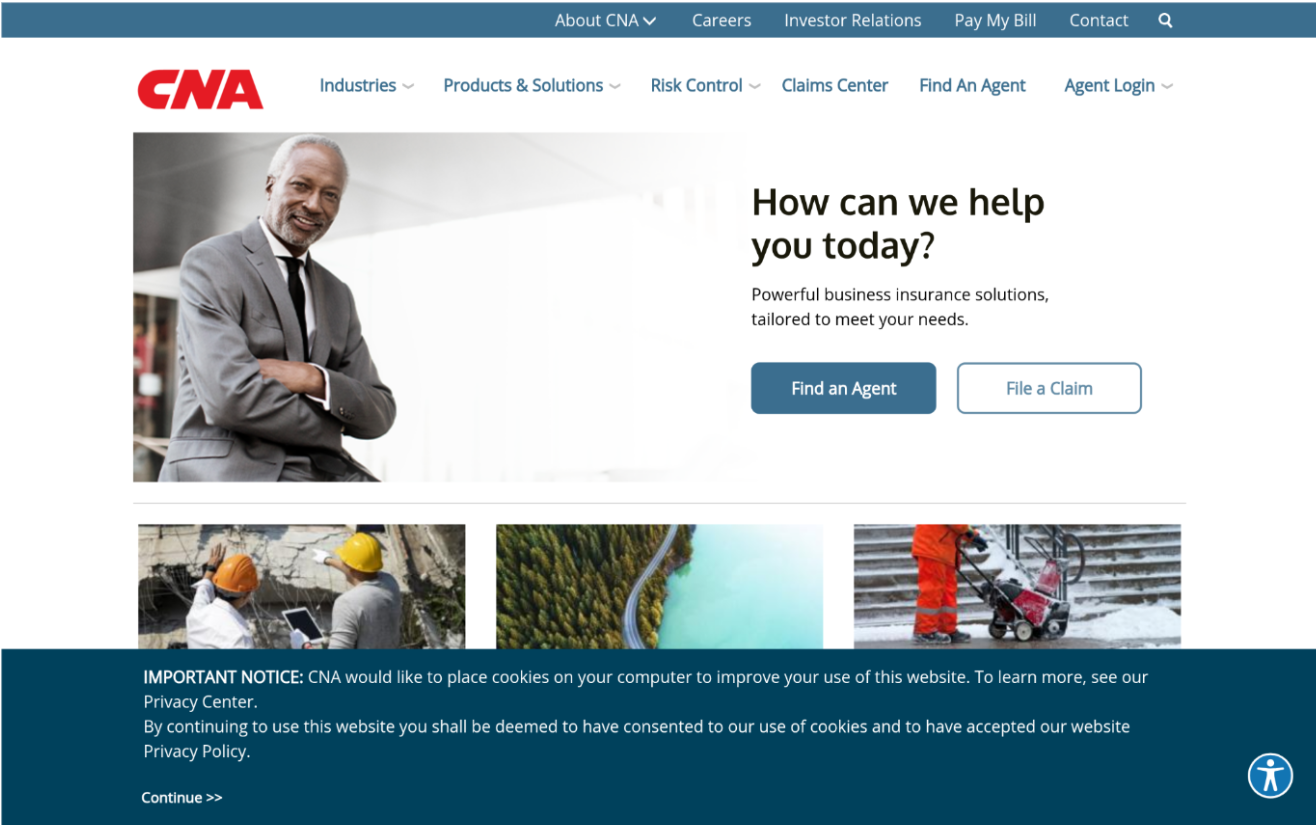
CNA Financial Corporation is a commercial property and casualty insurer with roots going back to 1853. They work across property, marine, casualty, workers' compensation, and loss-sensitive programs in the U.S., Canada, the UK, and beyond. Construction is one of their named customer segments, which means their underwriting experience in this space runs deep. As the seventh largest commercial insurer in the U.S., they distribute through independent agents, brokers, and managing general underwriters, giving contractors multiple access points.
Why Pick CNA for Top-Rated Insurance Companies?
Contractors who need a carrier with serious financial scale behind their policy will find CNA's 170-plus years of commercial insurance history genuinely reassuring. That kind of long-standing stability is hard to match, especially when a major claim hits and you need a carrier that won't flinch.
What the Reviews Show:
CNA's reputation among commercial policyholders tends to center on the breadth of their product portfolio and their consistency on complex claims. Brokers working in construction frequently cite CNA as a go-to for mid-to-large commercial accounts where financial strength ratings (think top-tier AM Best) matter as much as price.
3. Hiscox - Best for Small Business and Niche Market Insurance
What Is Hiscox's Main Business?
Hiscox is a specialty insurer with over 120 years of history, operating across 14 countries with more than 2,700 staff. They cover niche risks that standard carriers won't touch, including cyber threats, kidnap and ransom, and satellite damage, alongside traditional property and casualty lines. Their small business segment is large, with over 600,000 customers across sectors like architecture, engineering, consulting, and the artisan trades. Their AM Best A (Excellent) rating and FTSE 100 listing give them credibility that goes well beyond marketing copy.
Why Pick Hiscox for Top-Rated Insurance Companies?
Small contractors and artisan trade professionals often find that standard commercial policies don't fit the shape of their risk. Hiscox built its entire model around exactly that gap. Their specialty underwriting approach means coverage terms are written for the nuances of the work, not forced into a one-size template.
What the Reviews Show:
Hiscox has won "Insurer of the Year" six times in eight years at the Insurance Times Awards, which is the kind of recognition that reflects sustained performance, not a one-off result. Customers in niche trades appreciate the specificity of the coverage and the clarity of the policy language (clearer than most, which is saying something in this industry).
4. Nationwide - Best for Insurance and Retirement Plan Options
What Is Nationwide's Main Business?
Nationwide is one of the largest insurance and financial services companies in the U.S., founded in 1925 and ranked No. 72 on the 2025 Fortune 500 list. They cover auto, homeowners, business, farm, life, and commercial insurance, plus retirement plans, annuities, and mutual funds. Their scale is large: nearly 32,000 retirement plans and close to $200 billion in participant assets under administration. For contractors who want a single carrier relationship covering both business and personal lines, Nationwide's breadth is genuinely useful.
Why Pick Nationwide for Top-Rated Insurance Companies?
Business owners who want to consolidate coverage across commercial liability, commercial auto, and long-term financial planning under one roof will find Nationwide's product range covers that ground without forcing multiple broker relationships. Their A+ rating from Standard and Poor's signals the kind of financial strength that matters when claims volume spikes after a major weather event.
What the Reviews Show:
Nationwide has earned a DALBAR Customer Experience Excellence Award for six consecutive years, which reflects real policyholder satisfaction over time, not just a strong claims year. Reviews from small business customers note that the multi-policy relationship tends to smooth out the claims process, particularly when both commercial and personal lines are involved (convenient in ways that aren't obvious until you actually need it).
5. Thimble - Best for On-Demand Business Insurance for Small Businesses
What Is Thimble's Main Business?
Thimble is a digital insurance platform built for speed and flexibility, letting small businesses get coverage by the job, month, or year through an app, website, or phone. They cover over 300 professions with products spanning general liability, professional liability, errors and omissions, business owners policies, commercial property, workers' compensation, cyber, and equipment insurance. Founded in 2015 and acquired by Arch Capital Group in 2023, they've delivered more than 170,000 policies. Policies are underwritten by Markel Insurance Company and National Specialty Insurance Company, both AM Best-rated carriers.
Why Pick Thimble for Top-Rated Insurance Companies?
Solo contractors or small crews who pick up short-term jobs without year-round coverage needs will find Thimble's by-the-job structure genuinely cost-effective (starting around $17/month, which undercuts most traditional options). The digital-first underwriting model cuts the back-and-forth out of the process, so getting a quote and binding a policy can happen in minutes.
What the Reviews Show:
With 86% five-star ratings across 621-plus Trustpilot reviews, Thimble's customer feedback is notably consistent. Speed and simplicity are central to most of the positive sentiment, with users calling out how fast the certificate of insurance arrives after purchase. That kind of turnaround is rare at this price point.
Evaluation Criteria and Research Approach
Building a shortlist of top-rated insurance companies for Florida contractors started with a broad sweep of publicly available sources. Review platforms, insurer directories, state insurance department databases, and official company websites all contributed raw material to the initial pool.
Assembling Information for Analysis
The research began by pulling names from multiple directories and listing platforms relevant to commercial and contractor insurance. Review aggregators, industry trade publications, and state-specific insurer lists were cross-referenced to build a longlist that reflected active providers in this space, not just nationally recognized brands. Case studies and documented policyholder experiences were also cataloged at this stage to establish a baseline of how each company actually performs at the account level.
Narrowing Down the Applicant Pool
Once the longlist was assembled, providers without verifiable track records in contractor or construction-specific insurance were removed. Review pattern analysis played a real role here: companies with sporadic or inconsistent policyholder feedback, regardless of company size, were deprioritized. The focus stayed on carriers and brokers where the review record told a coherent story about real-world service quality, not just marketing positioning.
Authenticating the Selected Items
Each shortlisted company was then cross-checked by comparing what their official websites claim against what verified reviews and third-party sources actually document. Where site claims around claims speed, coverage breadth, or financial strength couldn't be corroborated through independent sources, those claims were set aside. Real-world results, such as documented claims outcomes and policyholder retention signals, carried more weight than self-reported metrics.
The Authority Layer
Industry authority signals were factored in at this stage. Award recognition from credible insurance industry bodies, mentions in trade and financial publications, and participation in recognized rating programs like AM Best, J.D. Power, and DALBAR all contributed to each company's standing. These signals don't replace policyholder experience, but they add meaningful context about long-term stability and market credibility.
Top-Rated Insurance Companies Case Files
Finally, each company's dedicated service pages were reviewed alongside verified policyholder reviews and any published case studies. Service page depth matters because it reveals whether a company has actually thought through the coverage needs of a specific trade versus offering a generic policy with a contractor label slapped on it. Companies with clearly documented, trade-specific coverage structures and verifiable client outcomes ranked more favorably through this final filter.
Finding the Right Top-Rated Insurance Companies for Your Needs
No single carrier is the right fit for every contractor. The best match depends on your trade, your risk profile, your project size, and how much flexibility you need in a policy. Here's what to weigh before committing.
- Industry/Domain Experience: Look for carriers or brokers who specifically cover your trade, whether that's roofing, electrical, plumbing, or general contracting. A provider who understands the difference between jobsite liability for a remodeler versus a commercial builder will write better coverage.
- Features and Service Options: Certificate of insurance speed, same-day binding, and multi-line policy options matter operationally. If you need a COI before stepping on a jobsite Monday morning, your insurer's processing time is as important as the coverage itself.
- Pricing Structure: Florida premiums vary by county, trade classification, and claims history. Get multiple quotes and compare not just the premium but the deductibles, sub-limits, and exclusions that affect what you actually collect on a claim.
- Results Measurement: Track your claims settlement ratio and processing time after your first claim. That's the real test of whether your carrier's financial strength rating translates to actual performance.
- Industry Knowledge and Compliance: Florida's licensing requirements tie directly to your insurance obligations. A carrier or broker who understands state insurance department regulations and NAIC model laws will help you stay compliant without having to figure it out yourself.
Final Words
Choosing among Top-Rated Insurance Companies for Florida contractor work comes down to three things: financial strength you can verify, coverage terms that actually fit your trade, and a carrier or broker who moves fast when you need a certificate or a claim resolved. The companies here represent a range of approaches, from digital-first flexibility to deep commercial knowledge. As Florida's construction market grows, getting this choice right early protects everything else you're building.
Related reading: 3 Kinds of Insurance You Need to Protect Your Small Business
The weekly question
From obsession to clarity — one original question every week.
We answer one noisy topic at a time, in full. No daily roundup, no thread bait — just the question, the principles, and the system.